

LoanPro partners with KOHO on new Canadian products
Thu, 15th Oct 2026 (Today)
LoanPro has partnered with KOHO to support a new set of financial products for the Canadian fintech's members. The deal makes LoanPro part of the infrastructure behind KOHO's next generation of offerings in Canada.
Under the arrangement, KOHO will continue to control the customer experience in its mobile app and the design of its products, while LoanPro will provide the lending and servicing functions behind the scenes, including billing, servicing and reporting.
KOHO has served more than 2.5 million Canadians since launching in 2014. Its existing products include spending and savings accounts, credit-building tools and overdraft protection.
The partnership gives KOHO access to LoanPro's API-first platform as it develops additional products for its user base. The structure allows KOHO to build and launch products without creating all of the underlying lending and servicing technology itself.
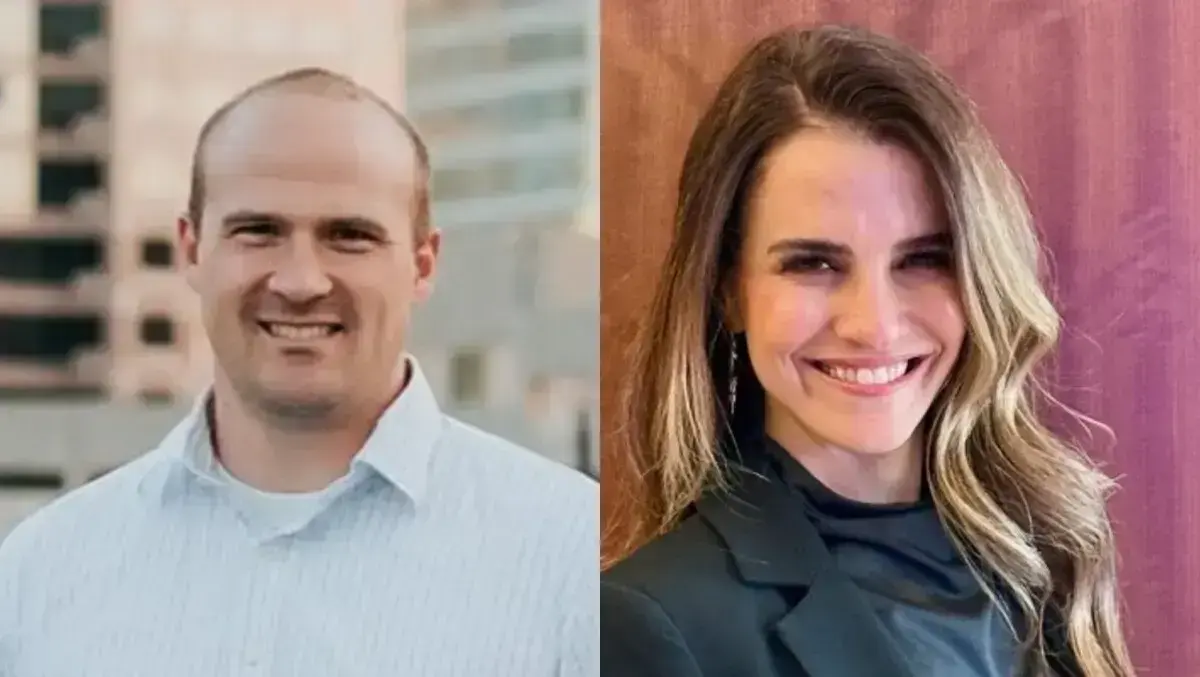
Rusen Baragiola, Chief Product Officer at KOHO, said the company wanted infrastructure that matched the pace of its product development.
"At KOHO, we're building fundamentally different products that help Canadians make real financial progress, and that requires infrastructure that moves as fast as we do," said Rusen Baragiola, Chief Product Officer at KOHO.
"We chose LoanPro for the flexibility to bring new products to market quickly and responsibly."
Canadian market
The companies pointed to the particular demands of the Canadian market as part of the rationale for the partnership. Financial products in Canada must meet national and provincial requirements, including rules that vary by province, such as those in Québec.
LoanPro's platform can be configured to reflect those differences, which may help fintechs adapt products for customers in different parts of the country. For KOHO, that means it can keep its app at the centre of the customer relationship while relying on LoanPro for core back-end processes.
The agreement also shows how fintech companies are continuing to separate front-end product design from the systems used to administer lending and credit products. In this model, consumer-facing brands focus on app design, marketing and product features, while specialist software providers handle operational tasks such as payment processing, account servicing and reporting.
Founded in 2015, LoanPro sells software to lenders, financial institutions and fintech groups. Its platform covers the full loan lifecycle, from origination to payoff, and is used to automate workflows, process payments, underwrite applications and manage collections.
Defined roles
In this partnership, the division of responsibilities is clearly set out. KOHO will remain responsible for what members see inside the app, while LoanPro will handle the systems that keep the products running after launch.
That model may appeal to fintech operators that want to expand their product range without taking on the cost and complexity of building every back-end function internally. It also reflects a broader trend in financial technology, where companies increasingly assemble products through partnerships rather than fully in-house development.
For LoanPro, the tie-up adds a Canadian fintech customer with a sizeable user base. For KOHO, it provides a platform to support the launch and servicing of additional financial products across Canada.
Rhett Roberts, Chief Executive Officer and Co-Founder of LoanPro, said the company sees its role as supporting KOHO's next phase of product development.
"KOHO has earned the trust of millions of Canadians by making money simpler, and we are proud to be the foundation behind what they build next," said Rhett Roberts, Chief Executive Officer and Co-Founder at LoanPro.
"Our job is to give KOHO a modern, configurable platform so its team can move quickly on new products, including meeting the Canadian requirements that make this market distinct."
The announcement comes as financial technology groups face continued pressure to broaden their product line-ups while managing regulatory and operational complexity. In Canada, that challenge can be greater because providers must account for both nationwide requirements and province-specific rules.
KOHO's decision to use an external platform for lending and servicing infrastructure suggests it wants to speed up product launches while keeping control of the customer-facing experience. The company's existing focus on everyday financial tools such as accounts, credit building and overdraft protection offers some indication of the market it is targeting, though the companies did not disclose details of the new products.
What is clear is that the next wave of those products will be built on LoanPro's platform, with KOHO retaining ownership of the member experience in its app and LoanPro responsible for billing, servicing and reporting.